Earnings: BBVA Exceeds €9 Billion in Profit in the First Nine Months of 2026 and Increases Lending by 20 Percent Year-on-Year
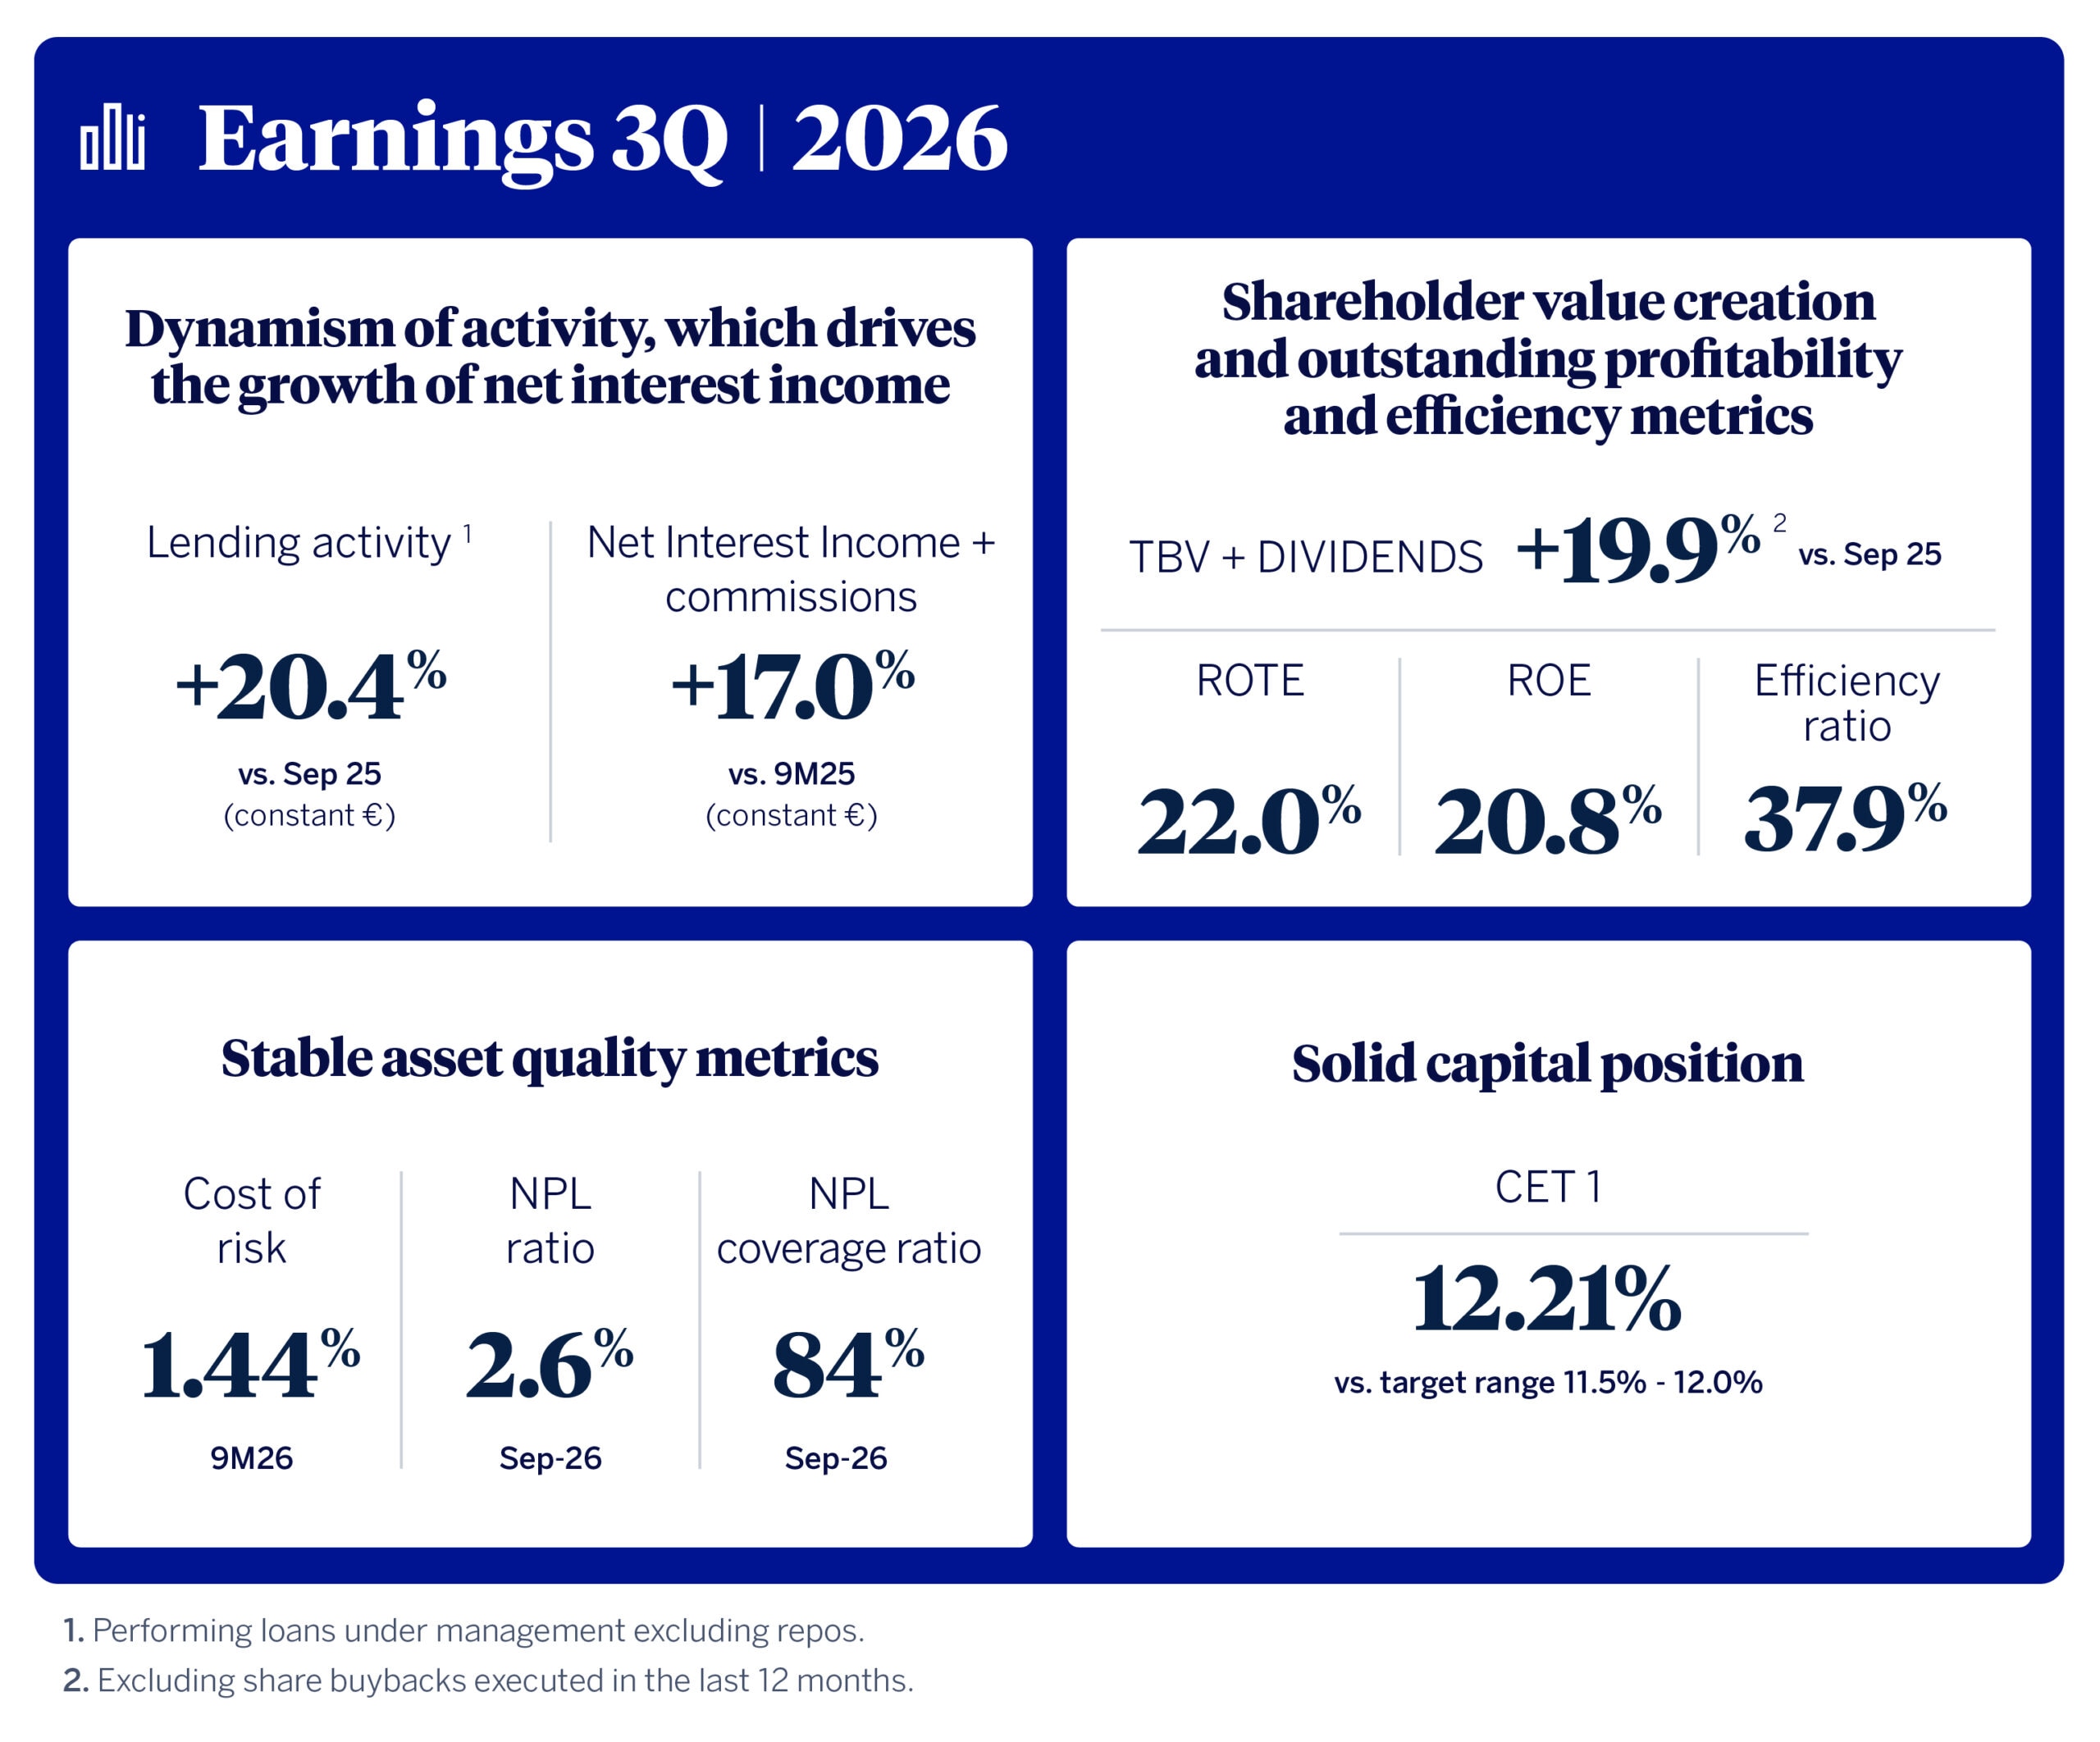
BBVA reported a net attributable profit of €9.07 billion for the period from January through September 2026, up 13.6 percent year-over-year (up 11.4 percent in constant euros) driven by strong recurring revenue (net interest income and fees and commissions). Earnings per share grew at a faster pace, rising 17.5 percent following the share buybacks carried out over the past 12 months. The Group maintains a distinctive combination of growth and profitability in Europe: lending increased by 20.4 percent year-over-year in constant euros¹, and ROTE reached 22 percent. The bank also boasts an industry-leading efficiency ratio of 37.9 percent and a strong CET1 capital ratio of 12.21 percent.
Press kit
“We have delivered excellent results. With a profile that continues to improve year after year, we continue to demonstrate our unique ability to combine growth and profitability. Our loan portfolio has grown by more than 20% over the past year, well ahead of our European peers. And we maintain a 22% return on equity, the highest in Europe. Since 2020, our contribution to society through lending has increased by 70%,” said BBVA CEO Onur Genç.
In the first nine months of 2026, BBVA made progress in the execution of its 2025-2029 Strategic Plan and the financial targets established for the 2025-2028 period:
“We continue to make progress on our strategic plan, with a particular focus on AI-driven transformation. And we are already seeing tangible results that demonstrate the enormous potential of this technology to enhance the customer experience, streamline processes and boost team productivity”, said Onur Genç. This trend will accelerate with ‘The Frame,’ a common framework BBVA launched for the entire bank with the aim of transforming its operating model and developing, deploying, managing and governing AI agents at scale, with human oversight, security and control.
Breakdown of business activity and income statement
Lending has continued to accelerate, with customer loans increasing by 20.4 percent year-over-year in constant euros at the end of September 2026. In particular, in BBVA’s main markets, Spain and Mexico, lending grew 7.3 percent and 12 percent, respectively, over the past 12 months.¹
For a better understanding of the income statement, the percentage changes shown below are expressed in constant euros unless otherwise indicated, i.e., excluding currency variations.
At the top of the income statement, net interest income increased by 17.8 percent year-over-year, reaching €23.24 billion, supported by strong business momentum, particularly in Türkiye, South America and Mexico. Net fees and commissions income stood at €6.91 billion (up 14.5 percent year-over-year), mainly due to growth in payment methods and asset management. The sum of net interest income and net fees and commissions, which together represent recurring revenue from the banking business, amounted to €30.15 billion, a 17 percent increase.
Also on the income side, the strong performance of net trading income stands out, increasing by 5.6 percent, supported by solid results in the Rest of Business area and Mexico.
Gross income reached €32.07 billion from January to September, up 16.3 percent year-over-year, slightly outpacing operating expenses (positive jaws), which increased by 16 percent to €12.17 billion. Meanwhile, the efficiency ratio stood at 37.9 percent. It is important to note that the increase in expenses was impacted by non-recurring items, such as VAT payment adjustments in the second quarter of 2025 and 2026 and voluntary staff departures in 2026. Excluding these effects, expense growth would have been 13.8 percent year-over-year, with an 81 basis-point improvement in the efficiency ratio.
Due to all of the above, operating income reached €19.90 billion, up 16.5 percent year-over-year.
In the current context of growing lending by the bank, impairment losses on financial assets increased by 22 percent, although risk indicators remained stable. The cumulative cost of risk since January stood at 1.44 percent, the NPL ratio was 2.6 percent and the coverage ratio was 84 percent.
The BBVA Group reported a record net attributable profit of €9.07 billion in the first nine months of 2026, up 11.4 percent year-over-year (up 13.6 percent in current euros). Earnings per share grew at an even faster pace (up 17.5 percent in current euros), thanks to share buybacks over the past year. In the third quarter of the year, net attributable profit was €3.02 billion, an increase of 14.4 percent over the same period of the previous year.
These results have enabled the Group to maintain a strong capital position while delivering high shareholder remuneration. The CET1 ratio stood at 12.21 percent at the end of September, above the bank’s target range of 11.5 to 12 percent. In this regard, on October 15, BBVA shareholders received a gross cash dividend of €0.37 per share charged against 2026 earnings. This figure is nearly 16 percent higher than in 2025 and represents the highest interim dividend in the bank’s history. Furthermore, the bank has a new extraordinary share buyback program underway worth €2 billion. It recently completed the first €1 billion tranche and has begun the second €1 billion tranche.
In the first nine months of 2026, BBVA has continued creating value for its shareholders. Tangible book value per share plus dividends stood at €10.92, which represents a 19.9 percent increase year-over-year, excluding the effects of share buybacks carried out over the past 12 months.
In terms of profitability metrics, ROE reached 20.8 percent through September, while ROTE was 22 percent. BBVA maintains a unique combination of growth and profitability. Since 2023, this has allowed the bank to increasingly distinguish itself from its comparable European peers in both metrics.
Business areas
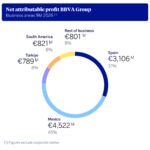
In Spain, corporate lending, consumer lending and card segments drove lending activity to 7.3 percent year-over-year¹. Net attributable profit reached €3.11 billion from January to September. Recurring income performed particularly well: net interest income increased by 3.4% year-on-year, while net fees and commissions rose by 2.3%. Risk indicators remained solid, with a cost of risk of 0.33 percent, an NPL ratio of 2.9 percent and a coverage ratio of 72 percent.
In Mexico, lending rose by 12 percent year-over-year¹, driven largely by corporate lending and positive contributions of all retail segments. On the income statement, all revenue streams performed well, although the strength of net interest income (up 8.5 percent) stood out. The efficiency ratio also stood out, remaining the best in the sector at 30.7%. Net attributable profit was €4.52 billion, an 8.4 percent increase year-over-year. The cumulative cost of risk improved to 3.19 percent, while the NPL and coverage ratios stood at 2.86 percent and 111 percent, respectively.
In Türkiye, the increase in lending in local currency stood out (up 40.1 percent)¹. Net attributable profit reached €789 million, a 21.8 percent increase year-over-year in current euros, driven by the strong performance of recurring revenue. In terms of risk indicators, the NPL ratio was 4.2 percent, the coverage ratio was 76 percent and the cumulative cost of risk was 2.55 percent.
In South America, the loan portfolio grew by 14.6 percent compared with September 2025¹. Net attributable profit reached €821 million, up 42.1 percent year-over-year in current euros, driven by the positive performance of recurring revenue in the region’s main countries. Colombia contributed €278 million, Peru €276 million and Argentina €102 million. The NPL ratio stood at 3.8 percent, the coverage ratio was 89 percent and the cumulative cost of risk was 2.72 percent.
Finally, in the Rest of Business area, the loan portfolio increased by 68.6 percent year-over-year¹, mainly due to strong growth in corporate lending in the USA, Europe and Asia. Net attributable profit grew by 58.5 percent to €801 million, supported by net interest income (up 40.2 percent) and net fees and commissions (up 32.1 percent). Meanwhile, the efficiency ratio improved over the past 12 months to 42%. The NPL ratio remained very low (0.3%), as did the cumulative cost of risk (0.11%), while the coverage ratio stood at 84%.
¹Performing loans under management excluding repos. In the case of Mexico, in accordance with local accounting standards.
About BBVA